Here’s the uncomfortable truth: only 17 U.S. states require high school students to take a personal finance course, according to the 2025 NGPF State Financial Education Policy Report. That leaves two-thirds of American teens heading into adulthood without a single lesson on budgeting, saving, or credit. Money management for teens isn’t optional anymore — it’s urgent.
Why Money Management for Teens Matters Now
The 2026 Everfi State of Teen Financial Literacy report surveyed 161,900 high school juniors and seniors. The findings are stark:
- 59% feel unprepared to set up and follow a budget
- 57% say they’re not ready to manage checking and savings balances
- 84% say they plan to invest someday — but 70% find investing intimidating
- Only 24% of teens say they understand how to create and stick to a budget
The average teen also spends $60 per week on food alone, often without tracking it Teens Survey. And 56% admit to impulse buying at least once a week, with social media as the main trigger.
These aren’t character flaws. They’re knowledge gaps — and money management for teens can close them.
Step 1: Understand Income First
Before anything else, a teen needs to know exactly how much money is coming in. Income sources at this age typically include:
- Part-time job wages
- Allowance from parents
- Cash gifts (birthdays, holidays)
- Gig work (babysitting, lawn mowing, tutoring)
If your teen has a part-time job, they’ll likely need a checking account for direct deposit. Most employers don’t mail checks anymore. Setting up that account is the first practical step in real money management for teens.
Step 2: Build a Budget for Money Management for Teens
Budgeting doesn’t need to be complicated. For a teen, a three-bucket system works well:
| Bucket | Purpose | Suggested % |
| Needs | School supplies, transportation | 50% |
| Wants | Entertainment, food, clothes | 30% |
| Savings | Future goals, emergency buffer | 20% |
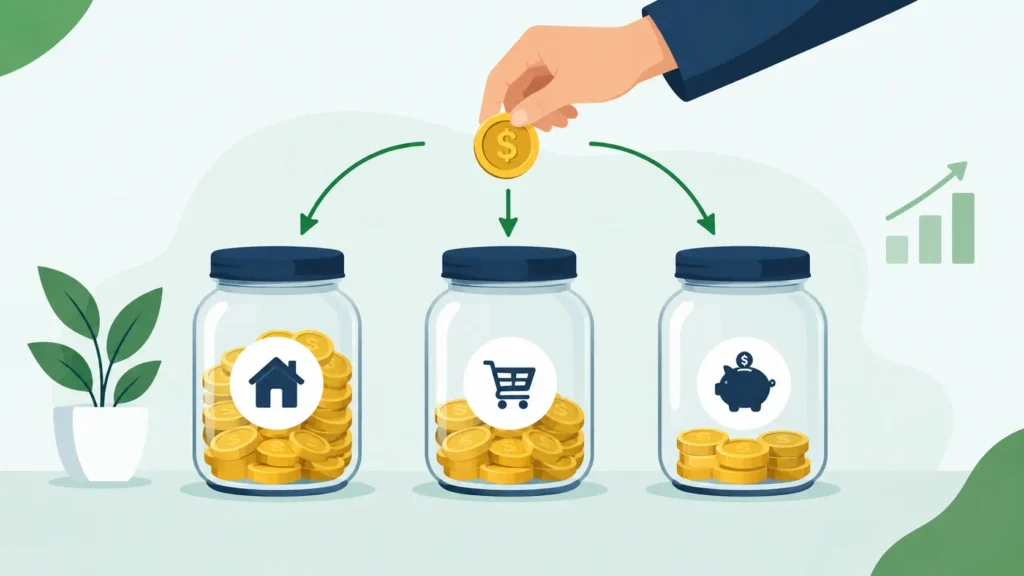
This is the 50/30/20 rule, recommended by NerdWallet and Citizens Bank as an accessible starting point for new budgets. A teen earning $400/month from a part-time job would set aside $80 automatically for savings — no debate, no willpower required.
The key phrase is pay yourself first. NerdWallet’s 2025 Savings Report found that people who automate savings before spending are significantly more consistent than those who save what’s “left over” at the end of the month.
Step 3: Open the Right Accounts
A teen under 18 needs a joint account co-owned with a parent or guardian. Options worth knowing:
- Capital One MONEY Teen Checking — no fees, no minimum balance, parent visibility
- Fidelity Youth Account — allows teens 13–17 to invest with parental oversight
- Credit union teen accounts — often higher interest rates than big banks
Once you open a checking account, open a separate savings account immediately. Keeping spending money and savings in the same account is the most common mistake young savers make. Out of sight genuinely means out of reach — and that’s the point.
Step 4: Tackle Impulse Buying
Impulse buying is the single biggest leak in a teen’s budget. Social media advertising is engineered to trigger it. A few practical defenses:
- Wait 48 hours before any non-essential purchase over $20
- Set spending alerts through mobile banking — most apps notify you the moment money leaves the account
- Unfollow brand accounts that trigger spending urges
Teen Shopping Habits report, the teens who track their spending — even informally — buy impulsively significantly less often than those who don’t.
Step 5: Money Management for Teens Starts with a Savings Goal
Teens save more consistently when the money is attached to something specific. Abstract savings goals (“for the future”) lose to concrete ones (“for a car by graduation”).
A useful framework: split savings into short-term (3–6 months, like a new phone) and long-term (1+ years, like a car or college fund). The average 16-year-old with a savings account has $1,200 saved, according to a 2026 analysis — but 35% of teens have no savings at all. A specific goal is what separates the two groups more than income level.
Step 6: Learn the Basics of Credit Early
You don’t need a credit card to understand credit — and money management for teens includes knowing why credit matters before signing up for one.
Key facts worth teaching:
- A credit score determines future loan rates, apartment approvals, and sometimes job offers
- Late payments damage a score for years
- 32% of teens don’t know the difference between a credit card and a debit card (Annuity.org)
Some teen savings accounts help build credit history passively. That’s a better starting point than a credit card.
Free Resources for Money Management for Teens
Paid courses aren’t necessary. High-quality free tools exist:
- Next Gen Personal Finance (NGPF) — free worksheets, PDF, and lesson plans (excellent for money management for teens PDF and money management for teens worksheet needs)
- Khan Academy Personal Finance — free video lessons on budgeting, taxes, and investing
- Consumer Financial Protection Bureau (CFPB) Youth Financial Education — government-backed, age-appropriate resources
Conclusion
Money management for teens comes down to six practical habits: know your income, build a budget, open the right accounts, control impulse spending, save toward a goal, and understand credit early. None of it requires a finance degree — just the right tools and a starting point.
Disclaimer: This article is for educational purposes only and does not constitute financial advice. Consult a licensed financial advisor for guidance specific to your situation.
Next up: Ready to go deeper? Read our cluster article on [printable budgeting worksheets for teens ] to find downloadable tools that put these habits into practice immediately.
FAQ Section
What is the best way to teach money management for teens?
Start with a simple budget using the 50/30/20 rule, open a joint checking and savings account, and set a specific savings goal. Real tools and practice matter more than theory. Free worksheets from NGPF make the process concrete.
Is there a free money management for teens PDF?
Yes. Next Gen Personal Finance (ngpf.org) offers free downloadable worksheets, PDFs, and lesson plans specifically designed for teen budgeting and money management.
How much should a teen save each month?
A common target is 20% of income. A teen earning $400/month should aim to save $80. The exact amount matters less than the habit — consistent small savings build stronger financial behavior than occasional large deposits.
What bank accounts are best for teen money management?
Capital One MONEY Teen Checking and Fidelity Youth Account are frequently recommended for no-fee, parent-monitored access. Credit unions often offer higher savings rates than big banks for teen accounts.
Why is money management for teens so important?
Only 17 states require a personal finance class for high school graduation (NGPF, 2025). Without formal education, most teens enter adulthood without budgeting or saving skills — and 70% of millennials now live paycheck to paycheck as a result.
What topics does a money management for teens book typically cover?
Most cover budgeting, saving, understanding credit, avoiding debt, and the basics of investing. Popular titles include I Will Teach You to Be Rich by Ramit Sethi (also available in a teen-adapted edition) and The Total Money Makeover by Dave Ramsey.

Financial enthusiast with 5 years of experience in the US market trends and personal wealth management