College costs hit $3,016 per month in living expenses alone for the 2025–26 school year, according to the College Board — and that’s before tuition. A student money management guide isn’t a “nice to have.” It’s a survival tool.
The hard part? Only 47% of undergraduates keep any kind of budget, per a 2024 College Ave survey. The other 53% are guessing — and running out of money before finals.
This guide fixes that with real numbers and a simple system that works even if you’ve never budgeted a day in your life.
Why Students Struggle With Money
The data from the CFP Board’s February 2026 study of 2,025 undergraduates is telling:
- 7 in 10 college students feel overwhelmed by their financial responsibilities (WalletHub, 2026)
- 64% feel confident managing basics like budgeting and saving — but that confidence drops fast when real bills arrive
- 30% say their top goal after graduation is paying off student loans
- Only 1 in 5 currently receive guidance from a financial professional
The gap between “I think I’m fine” and “I’m actually fine” is where most students lose money. A student money management guide bridges that gap before it becomes a debt problem.
Step 1: Know Exactly What’s Coming In
Before any budget works, you need a clear picture of monthly income. For most college students, money comes from:
- Financial aid disbursements
- Part-time or work-study wages
- Monthly allowance from family
- Freelance or gig income (tutoring, delivery, etc.)
Pro tip: financial aid hits once or twice a semester, not monthly. Divide the full disbursement by the number of months it needs to cover. Students who don’t do this math burn through money in October and beg in November.
Step 2: Build Your Student Money Management Budget
The College Board estimates average monthly student living costs for 2025–26 at:
| Expense Category | On-Campus | Off-Campus |
| Housing / Room | $900 | $700 |
| Food / Meal Plan | $400 | $300 |
| Transportation | $50 | $150 |
| Utilities | Included | $120 |
| Total Monthly | ~$1,740 | ~$1,660 |
A complete student money management guide always starts with these baseline numbers. Then add textbooks (~$107/month averaged across the year, per Education Data Initiative 2024), personal care, subscriptions, and entertainment.
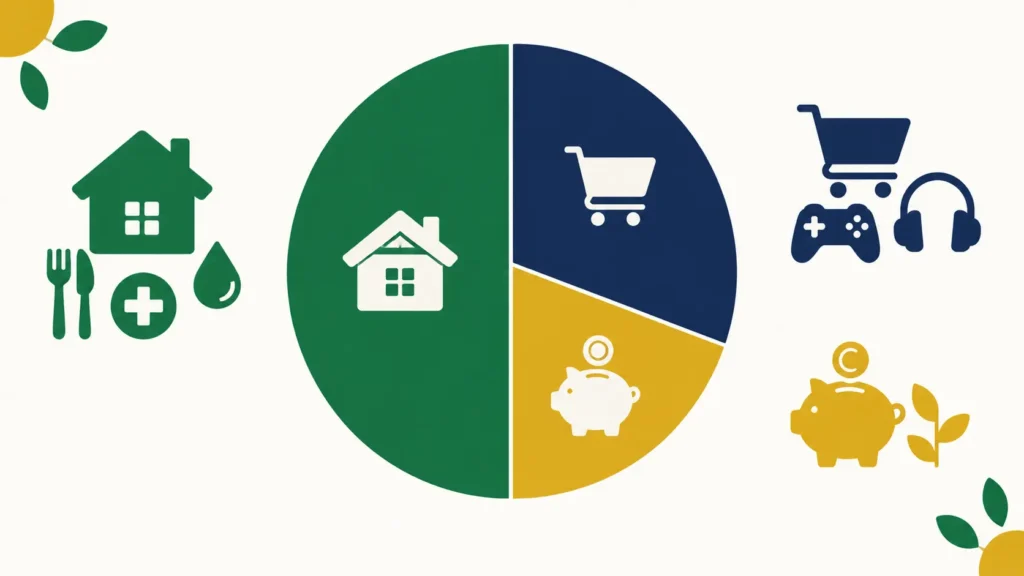
Once you know your costs, apply the 50/30/20 rule:
- 50% — Needs (rent, food, transportation, utilities)
- 30% — Wants (dining out, streaming, entertainment)
- 20% — Savings + debt repayment
NerdWallet recommends this framework specifically for college students because it’s flexible enough to handle irregular income without constant recalculation.
Step 3: Open the Right Bank Accounts
Mixing spending and savings in one account is the most reliable way to drain savings without noticing. Every student money management guide worth reading says the same thing: separate the accounts from day one.
Recommended setup:
- Checking account — for daily spending, linked to your debit card
- High-yield savings account (HYSA) — for emergency fund and short-term goals; top HYSAs currently pay 4.0–4.5% APY (Q3 2026, per Bank rate)
Top fee-free options for students:
- Ally Bank — online HYSA, no minimum balance
- Capital One 360 — checking + savings combo, no fees
- Local credit union accounts — often better rates than big banks
Step 4: Plug the Four Biggest Budget Leaks
The average college student spends $100+ per month on subscriptions they barely use, according to a 2026 college budget analysis. Combined with food delivery, impulse purchases, and unused gym memberships, the leaks add up to $200–$300/month for many students.
The four biggest drains and how to stop them:
1. Food delivery apps — Cook 3–4 meals a week at home. Average grocery spend: $263/month vs. $375+ for constant delivery or a full meal plan (SoFi, 2026).
2. Subscription creep — Audit every recurring charge. Cancel anything you haven’t used in the past 30 days.
3. Textbooks at full price — Rent via Chegg or use your college library’s reserve copies. Average savings: $300–$500/year (Education Data Initiative, 2024).
4. Owning a car on campus — A car costs $400–$700/month in total (payment, insurance, gas, parking), per DegreeCalc 2026. Campus transit and ride share is almost always cheaper for urban students.
Step 5: Build an Emergency Fund First
Students with high financial literacy are 72% more likely to save money than those without it, according to 2026 financial literacy data citing OECD research. But saving without a cushion first creates a fragile system — one flat tire wipes out three months of effort.
Start with $500–$1,000 in a dedicated savings account before putting money anywhere else. Once it’s there, save 10–20% of your monthly income toward a longer-term goal: a spring break trip, laptop replacement, or moving costs after graduation.
This is the step most college student money management guides gloss over. Don’t skip it.
Step 6: Understand Student Loans Before You Graduate
The average 2023 college graduate left school with $29,417 in student loan debt, per EBSCO’s Financial Literacy Among American College Students report. And 85% of borrowers expect repayment to cause financial hardship.
Yet only 43% of recent grads feel confident explaining interest rates.
What every student needs to know now:
- Know your loan services, interest rate, and exact balance today
- Understand the difference between subsidized and subsidized loans (interest on subsidized loans accrues during school)
- Set a calendar reminder for 6 months after graduation — that’s when federal loan repayment typically begins
- Explore income-driven repayment plans if your starting salary won’t cover standard payments
Step 7: Start Investing Early
A 20-year-old investing $25/month in a broad index fund at a 7% average annual return accumulates roughly $66,000 by age 65 with no additional contributions. Increase it to $50/month and that becomes $133,000.
(Note: Past market performance does not guarantee future results. Consult a financial advisor before investing.)
Options available to college students:
- Fidelity Youth Account — for students 18+, zero fees, fractional shares from $1
- Roth IRA — if you have earned income, up to $7,500/year (2026 IRS limit) goes in tax-free
- Round-up apps — Acorns rounds every purchase to the nearest dollar and invests the difference automatically
Free Tools for Student Money Management
You don’t need to pay for a money management for college students PDF or app subscription:
- NGPF.org — free worksheets and lesson plans built for young adults
- CFPB Money as You Grow — government-backed financial education resources
- YNAB — free 34-day trial plus free account for students enrolled at partner universities
- Your campus student money management center — 76% of students wish they had more help (KeyBank survey), yet most never visit these free on-campus resources
Conclusion
This student money management guide comes down to seven habits: know your income, build a real budget using actual 2026 cost data, open the right accounts, plug the four biggest leaks, build your emergency fund first, understand your student loans before graduation, and start investing early.
None of it is complicated. Most of it is just doing the math that 53% of students skip.
Disclaimer: This article is for educational purposes only and does not constitute financial advice. Consult a licensed financial advisor for guidance specific to your financial situation.
Next: Read our article on [printable budgeting worksheets for college students] to download the exact tools that put this student money management guide into practice immediately.
FAQ
What is a student money management guide?
A student money management guide is a step-by-step system for tracking income, building a budget, saving consistently, and avoiding debt during college. It covers the money management skills and tools specific to the limited-income, high-expense reality of campus life.
What are the best money management tips for students?
Track every expense for 30 days first, then build a budget. Separate checking and savings accounts, build a $500 emergency fund first, and cut the four biggest leaks: food delivery, unused subscriptions, new textbooks, and car ownership on campus.
Is there a free money management PDF for college students?
Yes. Next Gen Personal Finance (ngpf.org) offers free downloadable PDFs, worksheets, and lesson plans. Your college’s student money management center likely has printed guides, too.
What are money management examples for students?
Common examples include the 50/30/20 budget split, automating a $50 savings transfer every payday, tracking weekly grocery spend, and splitting rent with 2–3 roommates to cut housing costs by 40–60%.
What money management skills should every college student develop?
Core money management skills include budgeting, distinguishing fixed vs. variable expenses, understanding interest rates on loans and credit cards, setting short-term savings goals, and avoiding lifestyle inflation as income increases.
How much should a college student save each month?
With average living costs at $1,740–$3,016/month depending on campus, aim for 10–20% of take-home income in savings. Even $50–$100/month builds meaningful habits that carry into post-grad life.

Financial enthusiast with 5 years of experience in the US market trends and personal wealth management